I have been avoiding MNACT. Hong Kong(HK) has changed. Riot are back when convid 19 just got better in HK. But today something strike me, thinking if the price has offer a bargain. Distributable Income dropped 48.2% for Q3, reduced to 12.5% with top up from borrowings, and to later pay back with money from insurance. DPU for Q3 is 1.671cents and if you prorated the advance dividend of 1.07cents for 2 month period, it will be 1.665cents for Q4. What happened in Q4? I can only guess its due to convid 19.
Looking at 3 quarter results Y-on-Y is reduce by 0.8% after top up. Hence if the same thing happened every year, and if the insurance can be renewed every year, the impact is minimal. Current FY DPU would be likely 7.223cents, giving a 8.25% yield at a price of $0.875. If Q4 is affected due to convid 19, and continue to be so, expect a lower yield. Assuming 1.665 * 4 = 6.66cents or 7.61% yield.
Positive assumption: - Riot strength not as strong as before convid 19 or less violent (for now) - They seem to go to different Malls or places depend on their agenda, they cant be everywhere - life goes on with citizens - Hopeful Convid 19 will go away Negative assumption: - Repeat of what happened in November - Rental Reversion - University is just next door
I always wonder if a holding a REIT is better or selling when the profit is hit 3 years of dividend or more, that is profit is 3x the yield. The same question also pop up in InvestingNote, especially when prices has been going up all time high with current yield dropping below 5%. In this post, I will try to plot out and compare the difference in gain for Holding vs. Buy low sell high (BLSH).
Fun Fact Just before the GFC, CMT was trading at $3.5 with a yield of about 3.8%, CMT current yield is 4.8%, high but not crazy high yet. During GFC, CMT issue 9 for 10 rights, which mean when adjusted for the rights, CMT is now worth $4.52 pre-crsis.
Mapletree North Asia Commercial Trust Buy Criteria: 7% Yield Sell Criteria: 3 years worth of dividend from Gain
Ascendas Hospitality Trust Buy Criteria: 7% Yield Sell Criteria: 3 years worth of dividend from Gain
CapitaR China Trust Buy Criteria: 7% Yield Sell Criteria: 3 years worth of dividend from Gain
Capitamall Trust Buy Criteria:Close to 6% Yield Sell Criteria: 3 years worth of dividend from Gain
Mapletree Commercial Trust Buy Criteria: 6.5% Yield Sell Criteria: 3 years worth of dividend from Gain
Conclusion No one Reit is the same, investor's reaction to the price differ as well. Comparison show that one is better off holding AHT and CMT as the difference is minimal and CMT is definately a HOLD rather and BLSH. The comparison is base on hindsight so there are rooms for error in executing as well as broker's fees. For MNACT, there is a substantial gap in gains. 90% vs 112%, BLSH is the winner.
MCT show a unique situation. The price never come down low enough to reach 6% yield and rebound at 5.9% after selling off in 2016. LOL, if one stick to the TP, he would have missed the boat since 2016. However, he will be rewarded handsomely if he did catch in at the low. gain will turn out to be 120% vs 48.8% total gain. It's tought to be right all the time. So in conclusion, It is better off to hold on to your REIT unless there is a better investment (Just sold FLT for First Riet) or when the price is so high that the yield has reached GFC level of below 4% yield.Human nature, even with the comparison proof that holding is the better strategy , I am still tempted to sell! the immediate gratification! I need to find a way stop my hand from the sell button!
I had looked at Mapletree North Asia Commercial Trust (MNACT) when I started investing in late 2015. However a few reasons make me reluctant to invest in it then. High Gearing At almost 40% which may result in rights issues.Over the years I have learnt that rights may not be bad and give a good chance to buy more at a cheap price like the recent Frasers Logistic & Industrial Trust Rights issue.Most Mapletree Reits has high gearing. So it is unavoidable. Over the years since 2015, gearing still as high near 40%. Most of time, they issue placements rather than rights. Young Reit listed less than 6 years ( 3yrs in late 2015) Only 2 Properties in 2015 It had since grow to 9 properties
Festival Walk (Retail + Office, Hong Kong)
Gateway Plaza (Grade A Office, China )
Sandhill Plaza (Business Park, China)
6 Japanese Office Properties (Chiba, Tokyo, Yokohama)
MNACT to me is like a mirror of Mapletree Commercial Trust (MCT) but in oversea properties with Festival Walk as its core just like Vivocity with MCT. Festival Walk
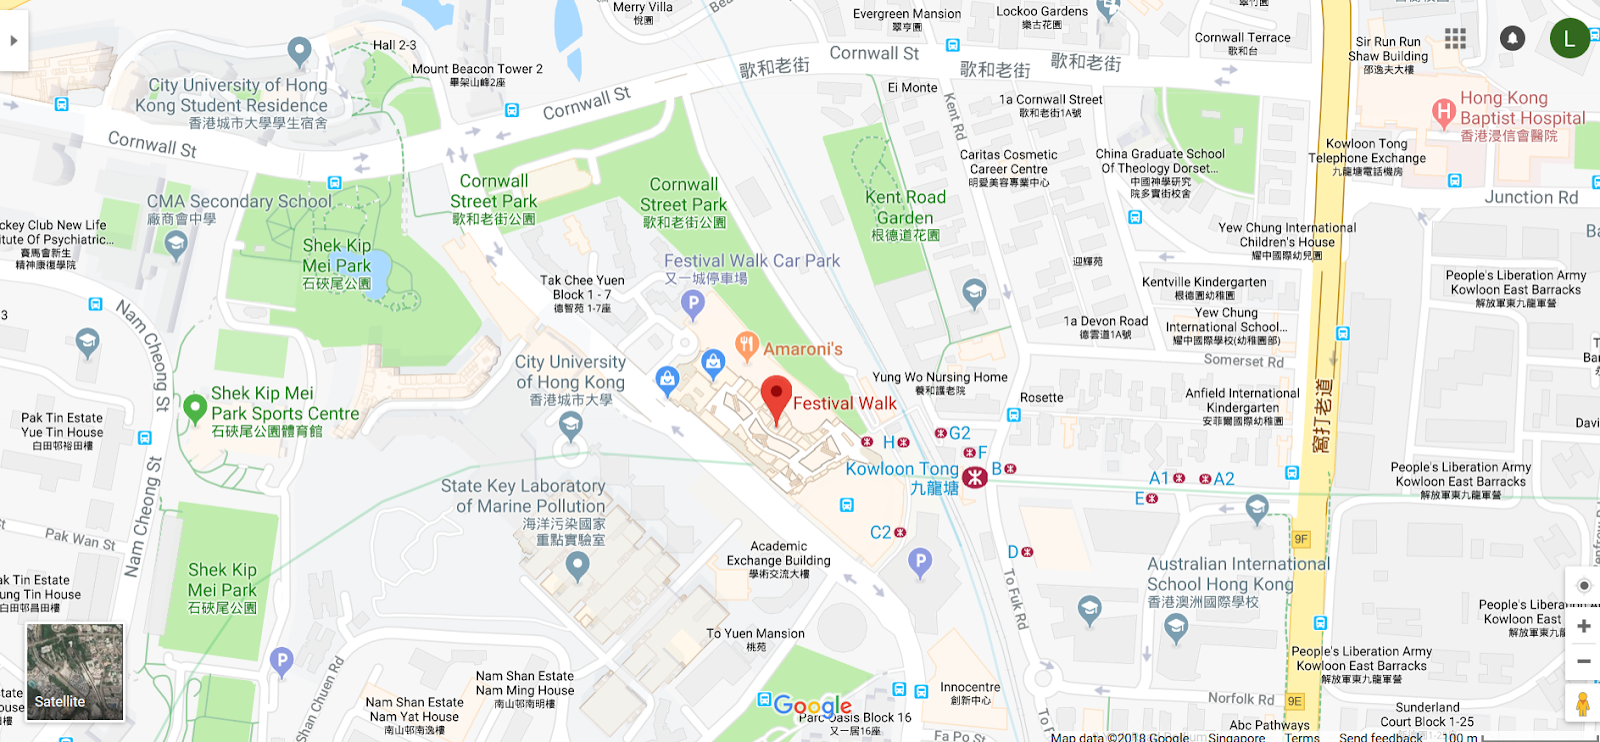
Festival Walk is located next to City University of Hong Kong, with ample nearby estates as well as international schools (Need to Zoom in Google maps to have more displayed). I believe these schools will attract properties demand and hence more people staying nearby Festival Walk and more footfall. The Kowloon Tong MTR is located nearby with a walkway link to Festival Walk. Festival Walk contribute 63% of MNACT Net Property Income.
DPU Growth
The manager did a good job growing the DPU which has been increasing with a CAGR of 4.65% for the past 5 years. Occupancy and Rental Performance
The occupancy rate at Festival Walk is amazing, keeping at 100% whereas the rest is pretty good too. Positive rental reversion for the last 4 quarters is also show a very good results. Expects room for further yield improvements for the Japan properties as some of the leases are currently under-rented (Source). Lease expiry for the next 2 years mainly come from Festival Walk but I think it won't haven any issue getting 100% occupancy rate.
Gearing Gearing is at 39%, however analyst expects this ratio to fall when its existing portfolio of assets
are revalued at the end of FY18, particularly given the sharp rise in
asset values in Hong Kong. (Source) Conclusion I like how MNACT have performed and grew over the years, DPU has been growing nicely. 1H2018/2019 Dividend is 3.807cents, 2H usually give a slightly higher dividends. Estimating a full year dividend to be 7.707cents, at a price of $1.10 gives a yield of 7%. PB ratio of 0.83. Risk for this Reit will be of the weakening of foreign currency against SGD as well as the economy of that region. And Festival Walk contributed 63% of Net Property Income which is a concentration risk as well. Vested @ 1.09