x
Showing posts with label CapitaR China Trust. Show all posts

Tuesday, 30 October 2018

CapitaRetail China Trust 2018 Q3 Result

CapitaRetail China Trust (CRCT) Q3 results give a few positives. This show that China's domestic consumption is strong as the middle income grows. Results also show rise in shopper traffics and sales of tenants. DPU increase 1.7% Y-on-Y, YTD DPU of 7.8cents present a 7.7% yield at the price of $1.36. Debt has been refinance and hence no refinancing needed till 2020.

Rental reversion
Rental reversion is tremendously high for properties acquired in 2017, CapitaMall Xinnan and Rock Square.


Conclusion
Gross revenue has fallen YTD 2018 in terms of SGD however NPI( Inluding Joint Venture Rock Square) has approximately the same as YTD 2017. However, Distribution amount is higher in 2018. This is likely because of the distribution for the divestment of Anzhen.

So once this distribution from Anzhen eased, DPU should drop. I believe CRCT's  management is confident the rental reversion will continue to increase to cover up the difference.

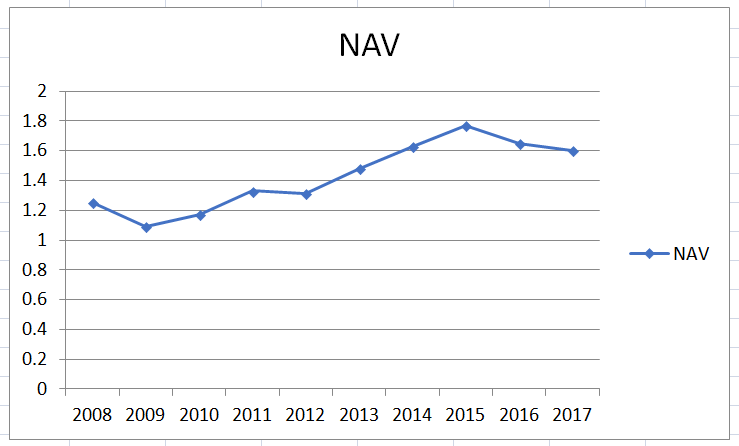
CRCT's NAV from Q2 $1.71 to $1.57, PB ratio is now 0.87. This is maybe due to depreciation of the RMB. Gearing at 35.7%, Interest cover 5.9x.


Vested @ $1.43
Read More

Monday, 6 August 2018

CapitaRetail China Trust


Singapore Retail Segment is facing headwinds from eCommerce, most malls now have cater to more F&B outlets. However China's retail segment has a better prospect as middle class grows and spend more. 

Comparing from the past results against 1st Quarter results, the recent placement (an increase of 10% shares) has diluted the DPU. the current DPU is supported by the capital distribution from a portion of the gain from the disposal of Anzhen.  Probably why the price tanked since FYQ4 results was released.

2nd Quarter results, Rock Square provide full quarter contribution. DPU increases with capital distribution from a portion of the gain from the disposal of Anzhen.

Forward looking: The Joint venture acquisition of Rock Square reported renewal revision of more than 20%. More than 50% of expiring leases are expect to renew from 2018 
to 2020.


DPU has a CAGR of 13.34%. Recent drops relates to the implementation of value added tax, divestment of Anzhen and the placement of shares.

1HFY2018 DPU of 5.39cents, assuming full year DPU of 10.76 cents which gives a current Yield of 7.3% with the price of S$1.47. Gearing is at a healthy 32.1%, interest coverage of 5.9x, PB ratio at 0.86.


Read More
Powered by Blogger.