x

Monday, 6 August 2018

Quick look at Raffles Medical Group


Base on this article, Raffles Medical Group (RMG) has 168 beds. RMG is to ramp up an addition of 200 beds in the extension wing, which effectively will more than double the revenue of hospital services. However the beds are coming in slowly, 50 beds during opening and another 50 in FY2019. This mean RMG's revenue will increase 56% over the next few years, excluding any effects from china operations.

Beijing and Shenzhen, where Raffles already operates clinics, want hospitals, too. Loo says he'll expand at a measured pace. "We want to make sure we will manage them well. We are not in any hurry." ---- Forbes Asia Interview with Loo Choon Yong
Read More

CapitaRetail China Trust


Singapore Retail Segment is facing headwinds from eCommerce, most malls now have cater to more F&B outlets. However China's retail segment has a better prospect as middle class grows and spend more. 

Comparing from the past results against 1st Quarter results, the recent placement (an increase of 10% shares) has diluted the DPU. the current DPU is supported by the capital distribution from a portion of the gain from the disposal of Anzhen.  Probably why the price tanked since FYQ4 results was released.

2nd Quarter results, Rock Square provide full quarter contribution. DPU increases with capital distribution from a portion of the gain from the disposal of Anzhen.

Forward looking: The Joint venture acquisition of Rock Square reported renewal revision of more than 20%. More than 50% of expiring leases are expect to renew from 2018 
to 2020.


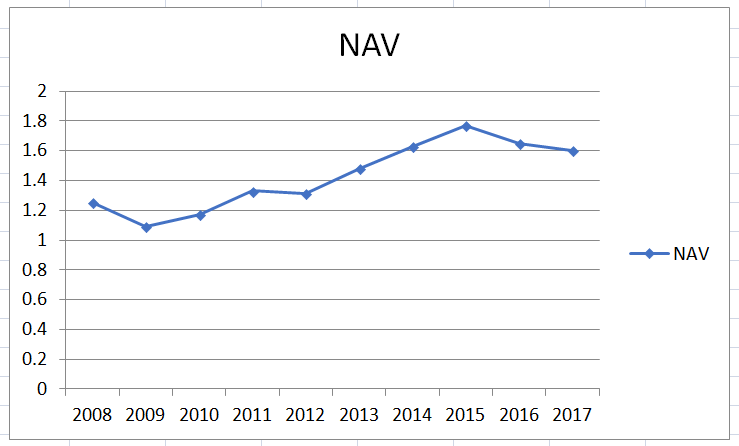
DPU has a CAGR of 13.34%. Recent drops relates to the implementation of value added tax, divestment of Anzhen and the placement of shares.

1HFY2018 DPU of 5.39cents, assuming full year DPU of 10.76 cents which gives a current Yield of 7.3% with the price of S$1.47. Gearing is at a healthy 32.1%, interest coverage of 5.9x, PB ratio at 0.86.


Read More

Sunday, 5 August 2018

Hui Xian Reit


Hui Xian Reit (HXR) 30% owned by ARA Asset Management, is make up of malls, offices, service apartments and hotels. The segments' profits are shown on the pie chart below.


Note:There is an estimate adjustment to mall and office in 2015 & 2016 from Chongqing Metropolitan Oriental Plaza

The Mall's profits has been increasing steadily, the recent drop could be due to the AEI at the malls of Chongqing Metropolitan Oriental Plaza as occupancy drop to 75.8% and also headwinds from eCommerce. The Malls at Beijing Oriental Plaza has direct access from Beijing's subway, another extension to another subway line is on the works, which give the mall footfall with easy accessibility.

Office faces headwind from new office supplies and slow down in china's growth.Office segment is still growing but Chongqing Metropolitan Plaza's office NPI drops. 

Service apartments has been stagnant, recent growth is due to converting 107 hotels rooms at Grand Hyatt Beijing to service apartments.

Hotel properties have the worst performance for HXR. Occupancy has not grew above 70% since IPO and was below 40% in 2014. Recently acquired two more hotels (Harbour Plaza Chongqing 66%, Sheraton Chengdu Lido Hotel 73.6%). Not sure what the management is thinking, however hotels only contribute 7% of profits.


The implementation of Value Added Tax in May 2016 greatly affected HXR's growth. NPI remain stagnant for the past 3 years.With the recent devaluation of RMB, base on last year's DPU of RMB0.268, which equals to 8.1% yield base of a price of RMB$3.31.

NAV is dropping, probably due to the increasing gearing affecting the total assets. Gearing at 23%, interest coverage 8.4x, NAV of RMB4.795. At a price of  RMB$3.31, PB ratio is at 0.69 with a yield of 8.1%. With low PB and high yield, anyone wants a piece of this Reit?


Read More
Powered by Blogger.